Case study · Total loss in Karlsruhe
150 euros in the report, 478 euros in the settlement
An older VW Touran, an economic total loss and a salvage offer from the insurer. A documented case from our office in Karlsruhe-Durlach, with the amounts from the report and the settlement.
All figures come from our report and the insurer's original letters. Supporting documents are included as images.
When the repair costs more than the car is worth
With older vehicles, an economic total loss is reached quickly. The insurer then doesn't pay for the repair, but for the replacement value minus the salvage value. Two figures therefore decide the payout: what the vehicle was worth before the accident, and what it is still worth afterwards.
Using a case from our office, we show how both figures come about, why the insurer reached a different salvage value than our report, and what determines which value finally applies.
Overview
The case at a glance
| Vehicle | VW Touran 2.0 TDI Highline, first registered 2005, almost 200.000 km |
|---|---|
| Date of accident | 6 August 2026 |
| Accident location | Karlsruhe · inspection and processing in Karlsruhe-Durlach |
| How it happened | Rear-end collision, impact to the rear, mainly bumper and tailgate |
| Liable insurer | AXA Versicherung AG |
| Repair costs | 3.286,33 € gross (after deducting earlier damage) |
| Replacement value | 1.900,00 € (private market, excluding VAT) |
| Result | economic total loss |
| Salvage value per report | 150,00 € |
| Salvage value per insurer | 478,00 € |
| Payout | 1.447,00 € |
| Time until settlement | 34 days |
Timeline
How it unfolded
6 Aug 2026
Accident and inspection
Another vehicle drives into the rear of the owner's car. The same day, she brings the Touran to our location in Karlsruhe-Durlach and commissions us to prepare the report.
10 Aug 2026
The report
Repair costs above the replacement value: economic total loss. We inform the owner the same day.
13 Aug 2026
The salvage offer
On behalf of AXA, ControlExpert reviews the report and submits a binding purchase offer of 478 €, valid until 3 September 2026.
9 Sep 2026
The settlement
AXA settles using the salvage value of 478 € and pays out 1.447 €.
6 August 2026
What we found on the vehicle
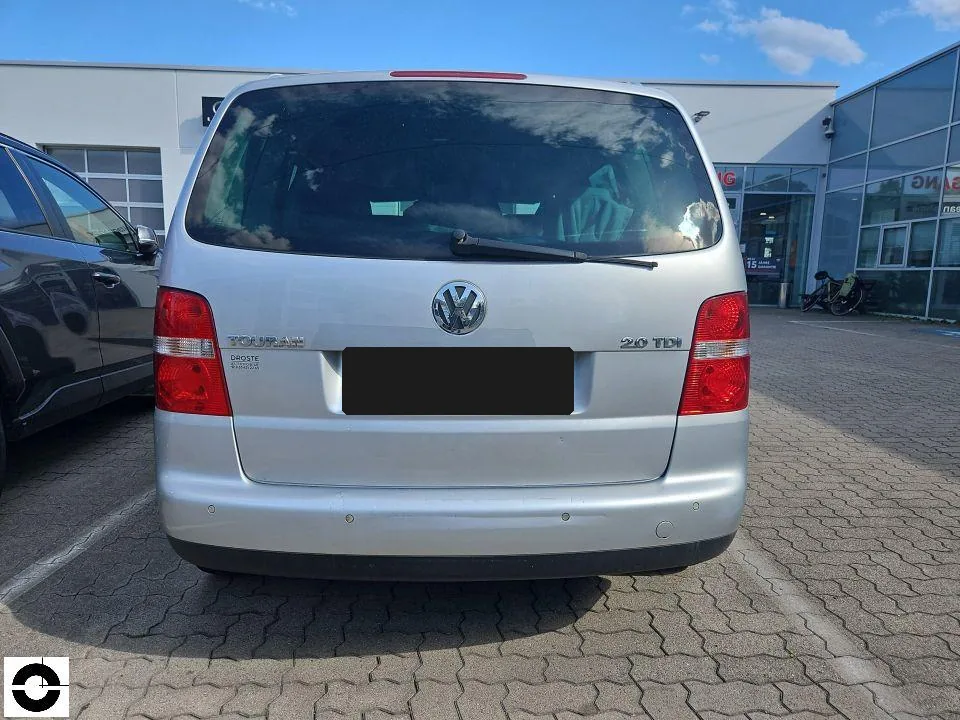
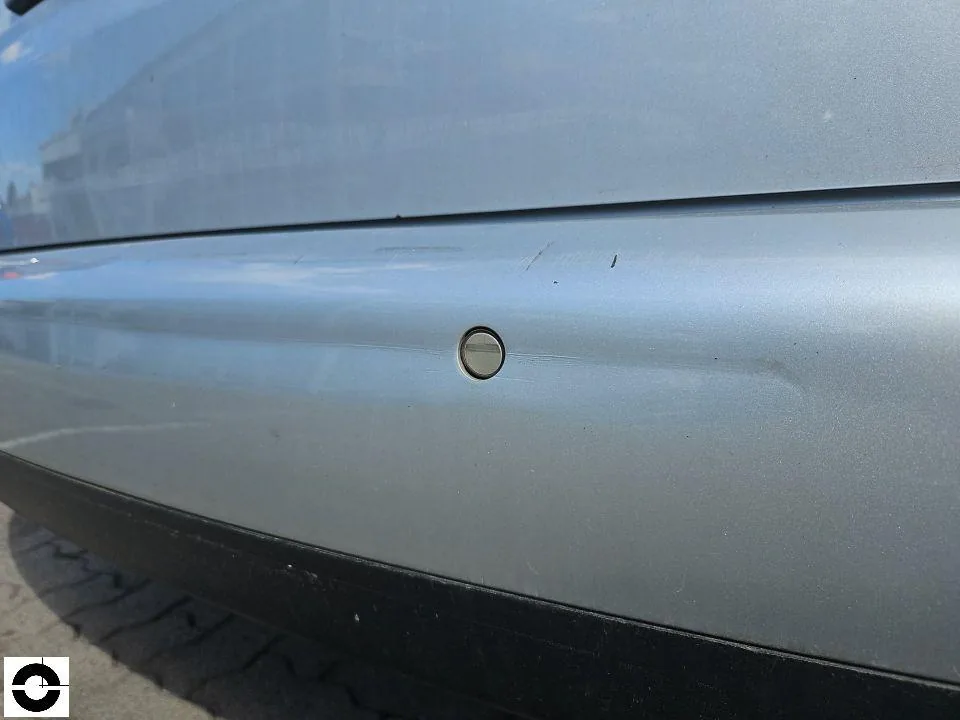
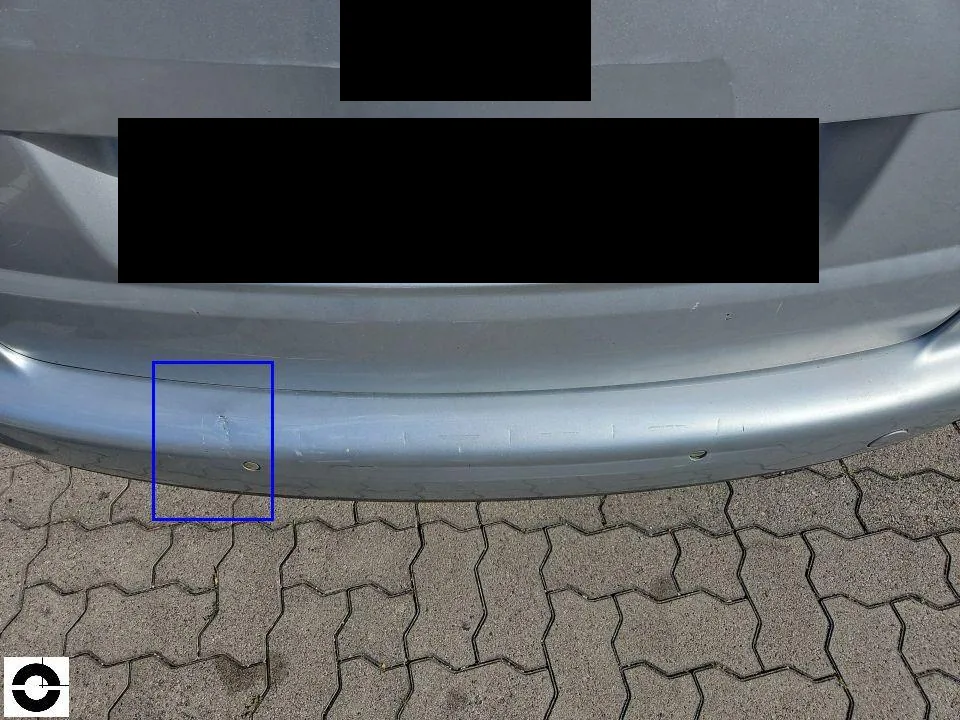
The Touran was hit in the middle of the rear. The tailgate was pushed in and needed repair, the inner rear parking sensors were damaged, and the lower bumper trim was scratched.
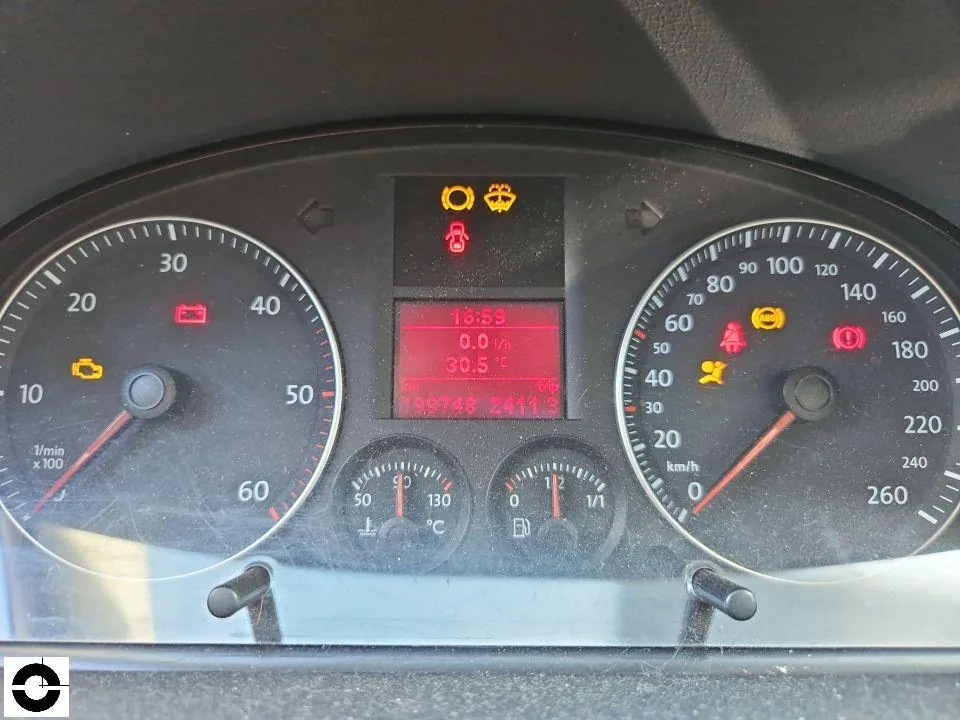
A vehicle with almost 200.000 km has a history, and that belongs in the report. We measured the paint thickness on the sheet metal to detect repainted parts and therefore repaired earlier damage. The values were around 90 to 120 µm, with nothing unusual. We also documented the visible earlier damage: minor dents and scratches all around, corrosion on the fender and wheel arch, and a rear bumper that was already pushed in.
Earlier damage doesn't belong in the accident bill
The rear bumper was right in the damaged area, but was already damaged before the accident. We therefore removed it from the calculation, as well as a proportionate share of the tailgate paintwork. Of an initial 4.466,93 € gross, 3.286,33 € of repair costs remained after these deductions.
This is not a favour to the insurer, but a prerequisite for a reliable report. A report that bills earlier damage along with the rest can be challenged, and as a whole.
Rule of thumb
Earlier damage in the damaged area is deducted, not hidden. That is exactly what makes the remaining figures unassailable.
The replacement value: 1.900 euros
What would a comparable Touran have cost before the accident? Vehicles of this age are mostly sold privately. We therefore determined the replacement value on the private market, taking mileage, general condition and the documented earlier damage into account. Result: 1.900 €.
AXA adopted this value in its settlement without any deduction.
The repair costs of 3.286,33 € were therefore well above the value of the vehicle. A repair made no economic sense, and we did not recommend it.
Info box
VAT in a total loss
In a total loss, what matters is how comparable vehicles are traded on the market:
| Standard-rated (mostly newer vehicles from a dealer) | The replacement value includes 19 % VAT. |
|---|---|
| Margin scheme (used-car dealers under § 25a UStG) | It includes a small tax portion, which the courts estimate; in practice usually around 2 to 2.5 %. |
| Private market | It includes no tax. |
If you settle on the basis of the report without buying a replacement, the tax portion is deducted at first. It is reimbursed if VAT is actually incurred when you buy a replacement vehicle (§ 249 Abs. 2 Satz 2 BGB). In this case: the Touran was a private-market vehicle. The replacement value contained no VAT, so nothing was deducted.
10 August 2026
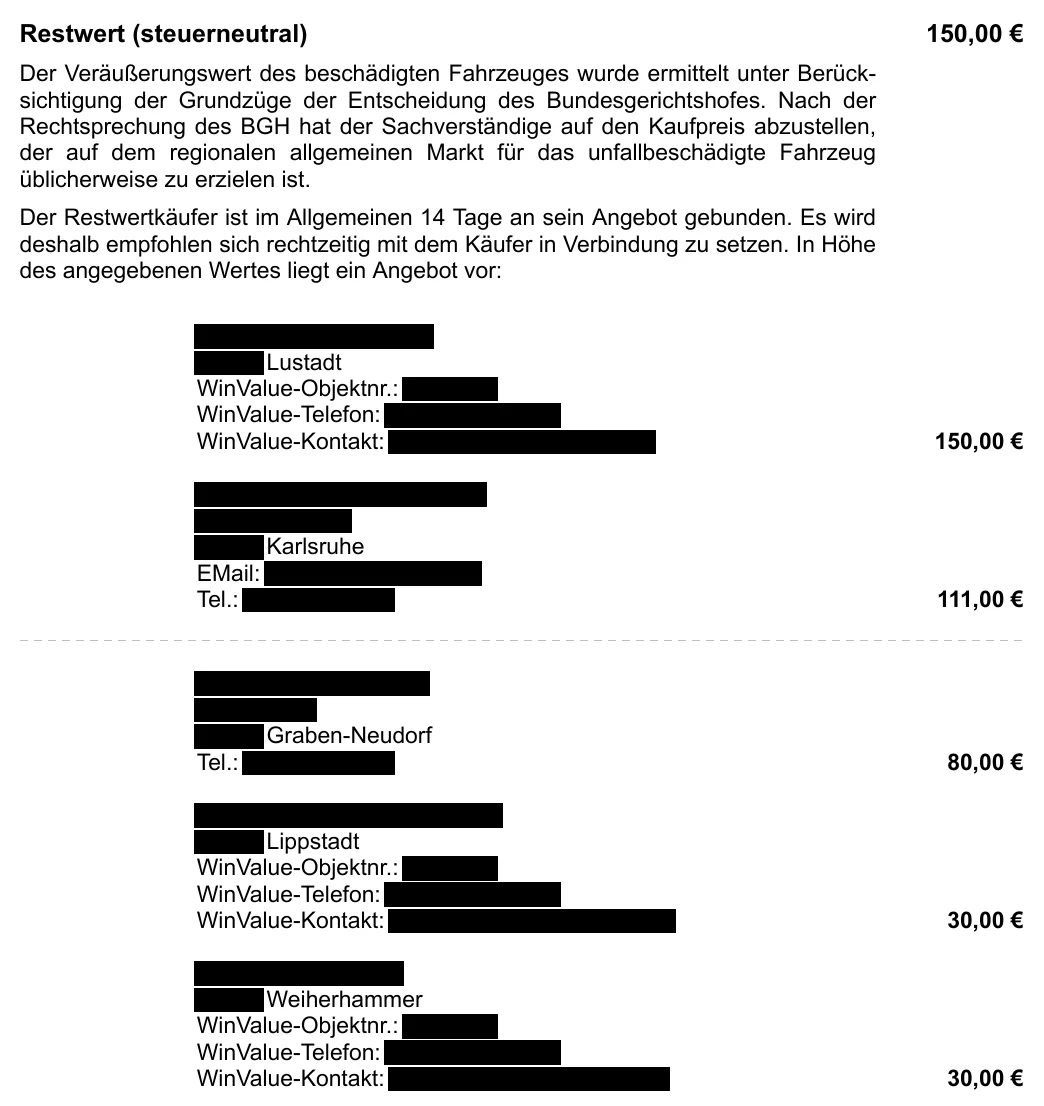
The salvage value: 150 euros according to the report
The salvage value is the amount the damaged vehicle can still fetch. It is deducted from the replacement value. The higher the salvage value, the less the insurer pays out.
We obtained five concrete purchase offers and listed them in the report with bidder and amount. They ranged from 30 € to 150 €, two of them from dealers in Karlsruhe and the surrounding area. We used the highest offer: 150 €.
We request offers from dealers in the region and additionally through the WinValue salvage exchange. Every bidder factors the cost of collection into their bid; a bidder further away is therefore no better off than a local dealer.
13 August 2026
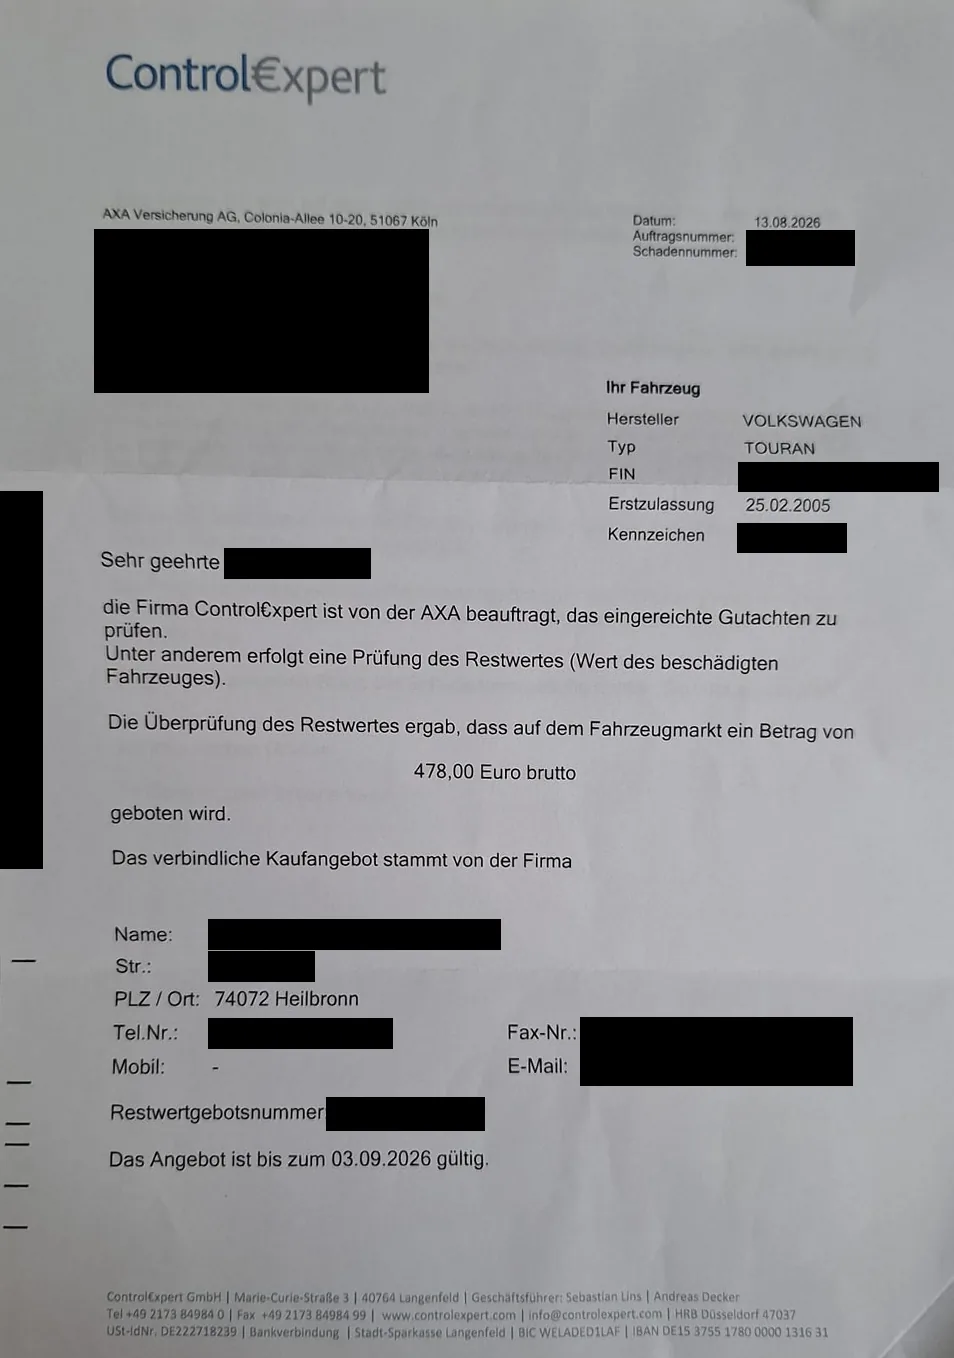
The insurer's offer: 478 euros
Three days after the report, the vehicle owner received a letter from ControlExpert, a review service provider that checks reports on behalf of AXA. The letter contained a binding purchase offer of 478 € from a buyer in Heilbronn, valid until 3 September 2026. According to the letter, the sale involves no costs, and the purchase price is paid in cash on handover if requested.
9 September 2026
AXA's settlement
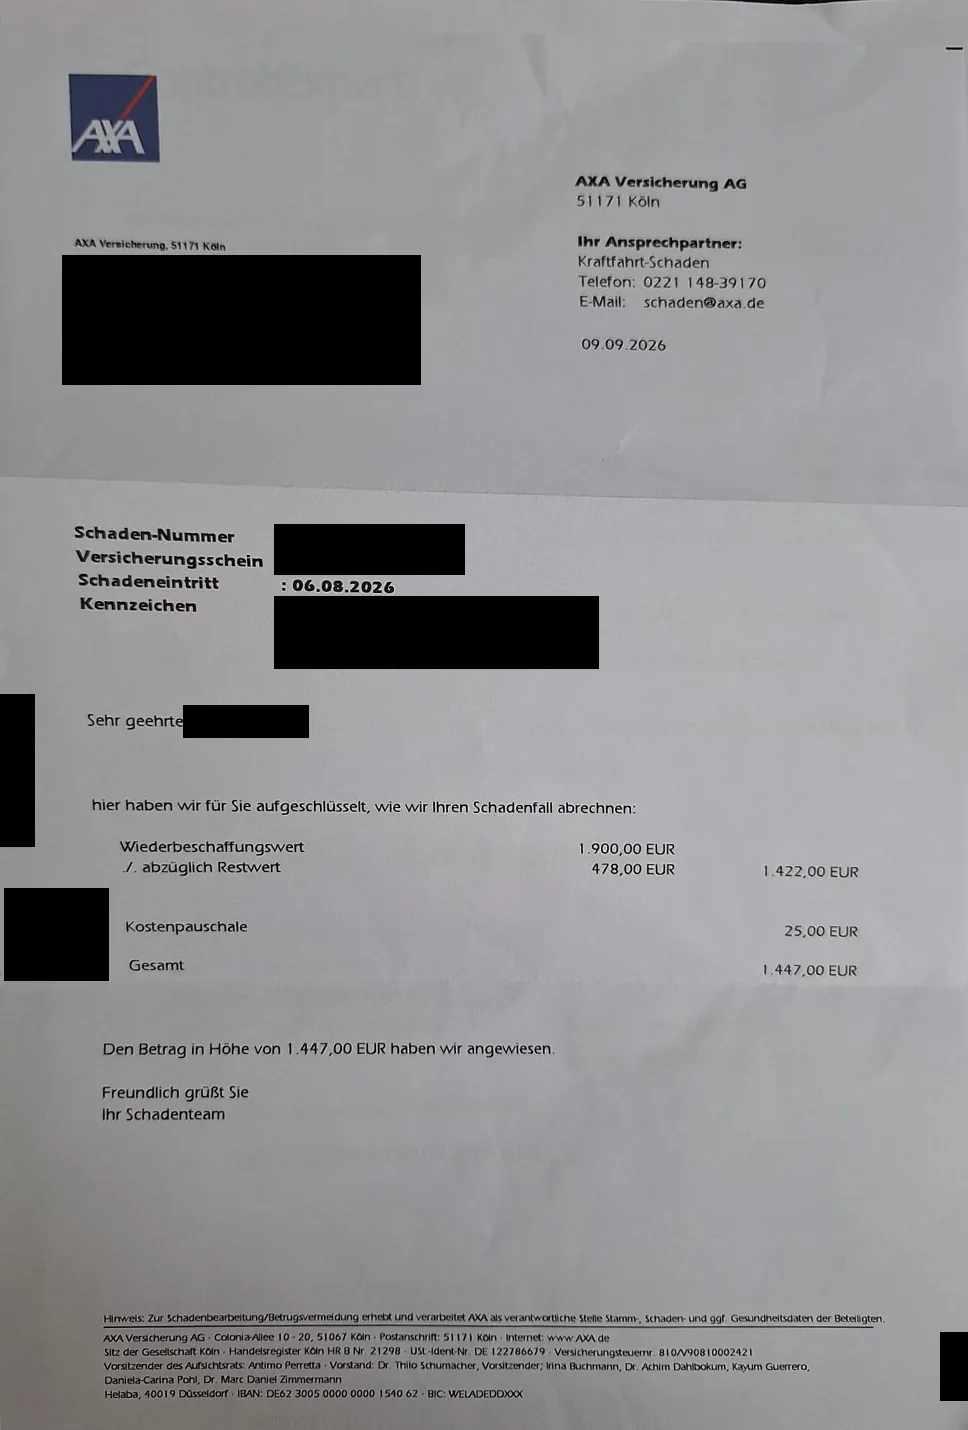
On 9 September 2026, AXA settled using this value:
| Replacement value | 1.900,00 € |
|---|---|
| minus salvage value | 478,00 € |
| Subtotal | 1.422,00 € |
| Flat-rate expenses | 25,00 € |
| Paid out | 1.447,00 € |
With the salvage value from our report, it would have been 1.775,00 €. The difference is 328,00 €.
Which salvage value applies?
This is where it gets legal, and the honest answer is: it depends on what happens to the vehicle.
The basic rule: the regional market. The Federal Court of Justice (BGH) has ruled several times that a private injured party may sell their vehicle at the salvage value determined by a report on the general regional market. They don't have to be referred to salvage exchanges or nationwide buyers, and they don't have to wait for an offer from the insurer (BGH, judgment of 27.09.2016, VI ZR 673/15).
The exception: the offer is available before the sale. If a significantly higher, binding offer reaches the injured party before the sale and they can accept it without effort, for example with free collection and cash payment, they generally have to take it into account (BGH, judgment of 01.06.2010, VI ZR 316/09).
Continued use: then the report stands. If the injured party keeps using their vehicle in a roadworthy and safe condition, the salvage value determined in the report generally remains decisive, even if the insurer presents a higher offer (BGH, judgment of 06.03.2007, VI ZR 120/06). The BGH names no minimum period of use for this. The well-known six-month period concerns a different question, namely the settlement of repair costs.
Rule of thumb
If you receive a salvage offer from the insurer after a total loss, you should decide before selling whether you want to keep driving the vehicle. After that, the decision is usually made.
Sources
Case law relevant to this case
Linked to dejure.org. This presentation does not replace legal advice.
How it turned out
The vehicle owner chose the payout. With the insurer's salvage value, the settlement came out 328,00 € lower than it would have with our report.
Putting it in context
What we can prove ourselves, and what we can't
What is documented are the figures from our report, the salvage offer of 13 August 2026 and the settlement of 9 September 2026. Whether the 328,00 € could have been enforced cannot be determined from these documents: under case law, that depends on whether and when the vehicle was sold or kept in use.
We did not submit a statement to the insurer in this case.
Summary
What you can take away from this case
- In a total loss, two figures count. Replacement value and salvage value together determine the payout. Here the replacement value was fully accepted; the dispute was only about the salvage value.
- Documenting earlier damage protects the report. Deducting the bumper lowered the repair costs, but made the replacement value unassailable.
- A salvage offer from the insurer has a deadline. Here, 21 days lay between the offer and the end of the deadline. The real decision is made during that time.
- Keep driving or sell is a legal question. If you keep using the vehicle in a safe condition, you can generally rely on the salvage value from the report.
- Ask before you sell. A short call to us before the vehicle leaves your driveway costs nothing.
The author
Who handled this case
Sascha Frieß
Owner · Expert appraiser
Business engineer (M.Sc., KIT) and managing partner. Before joining the office, he spent eight years in automotive consulting at Porsche Consulting, focusing on aftersales. Today, he handles damage and value assessments as well as claims settlement with insurers.
- M.Sc. in Industrial Engineering (KIT)
- Certified vehicle appraiser
- Damage and value assessment
- Claims settlement with insurers
He personally handled the inspection and the report in this case. Area covered: Karlsruhe, Ettlingen, Rastatt, Baden-Baden, Bruchsal, Bretten, Pforzheim and Landau in der Pfalz.
More about Sascha FrießFrequently asked questions
Salvage value, total loss and VAT
Do I have to accept the insurer's salvage offer?
May I keep driving my car after a total loss?
Does a six-month period apply to the salvage value?
What is the regional market for salvage value?
Is VAT deducted in a total loss?
Why do I get a letter from ControlExpert after the report?
Total loss in Karlsruhe or the surrounding area?
Call us before you sell your vehicle.
Mon–Sat 08:00–20:00